
Six Forces Reshaping the Waterproof Bag Industry
Six forces are moving the waterproof bag industry at once, and only three of them change what a buyer should do. Capacity is spreading beyond a single country, recycled and mono-material fabric is becoming a default specification, and direct-to-consumer channels are pushing pack geometry towards lower shipping volume. Floor automation, labour cost pressure and freight volatility are real but affect your unit cost far less than poor design does. This page ranks all six against the two decisions you actually make: which construction to specify, and which 500-piece order to place first. Each force ends with the concrete change it should cause in your technical pack.
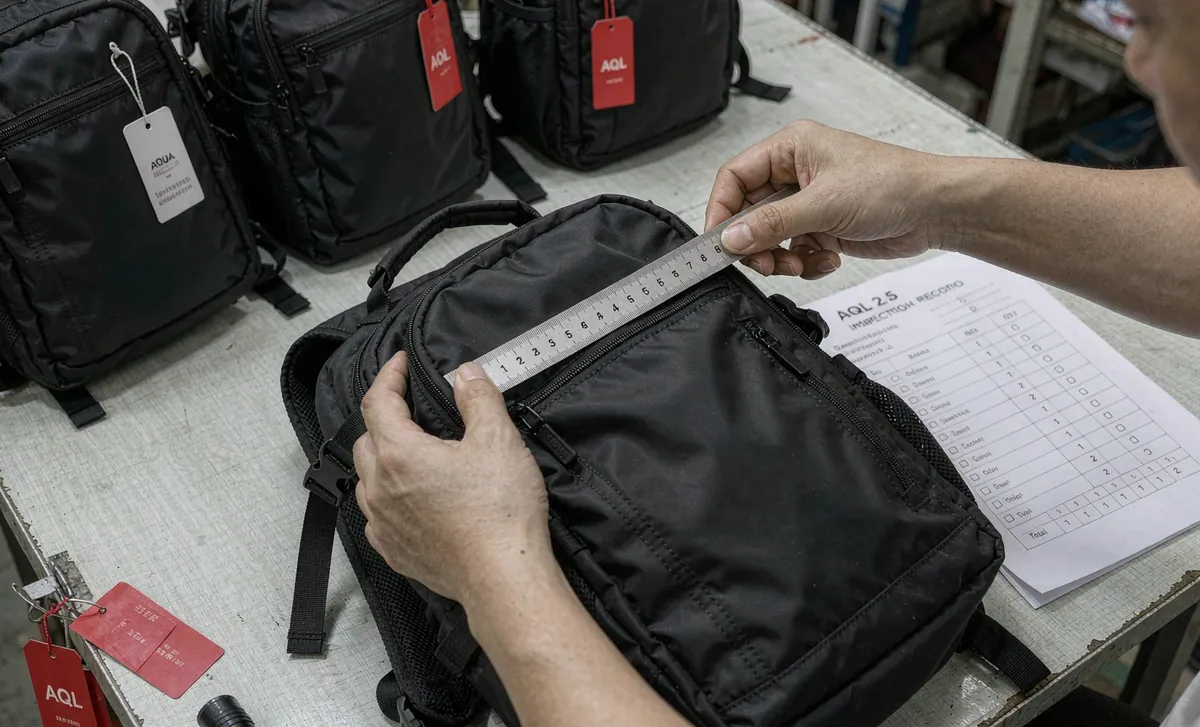
Table of Contents
- Where Bag Assembly Capacity Is Moving and Why It Matters
- Recycled and Mono-Material Fabric Adoption Across the Industry
- Direct-to-Consumer Channels Rewriting Pack Specification
- Automation on the Sewing Floor Since 2014
- Labour Cost and Skill Pressure in Bag-Making Districts
- Six Forces Ranked by Impact on a 2027 Sourcing Plan
- Freight, Tariff and Input Volatility in the Bag Trade
- What Industry Consolidation Does to Your Second-Source Options
- Multi-Country Sourcing and the Quanzhou Comparison
- What Demand Spikes Do to Your 35-50 Day Slot
- Sector Demand Shifts Across Paddle, Jobsite and Care
- Reading an Industry Trend Before You Commit 500 Pieces
- Compliance Documents the Industry Now Expects by Default
- Frequently Asked Questions
- People Also Ask
Where Bag Assembly Capacity Is Moving and Why It Matters
Bag assembly has been spreading outward for a decade, and the pattern is more specific than the phrase suggests. What moves first and fastest is the labour-intensive part: cutting, sewing and final assembly. What moves slowly, if at all, is the material base, because coated and laminated technical fabric, waterproof zips and moulded hardware are capital-intensive to make and are clustered near the polymer and plating industries that feed them. The practical consequence for a buyer is that a country can advertise a finished bag industry while still importing the two inputs that determine whether the bag is waterproof.
That split is why the comparison of sourcing countries cannot be made on wage rates. A site in a lower-wage country that imports its laminated rolls, its seam tape and its moulded closures carries the same material cost as a coastal China site, adds a longer material pipeline, and gains a wage saving only on the operations the product actually needs. For a welded dry bag, where material dominates and labour is a small share of the total, the saving is close to negligible. For a structured multi-pocket tool bag, where the operation count is high, it is worth measuring.
The third thing that moves is the compliance file, and it moves last. A new assembly country has to develop a supplier base that can produce a REACH declaration, a RoHS declaration and, where a claim is made, an ISO 811 test result on a lot-traced roll. That takes years rather than months, and until it exists the buyer is carrying the verification burden themselves. Our page comparing the production layout at this site shows what the material and capability split looks like where the two halves are still together.
Recycled and Mono-Material Fabric Adoption Across the Industry
Recycled content has moved from a marketing option to a line item on the specification sheet in most of the markets we serve, and the specification language has had to become more careful as a result. The claim that matters is not the percentage of recycled fibre in the face fabric; it is whether the whole laminate can be traced and declared. A face woven from post-consumer polyester bottle flake and then laminated to a virgin PU film is a genuine recycled-content product and is also a laminate that no mechanical recycler will accept at end of life. Both statements are true and both belong on the technical pack.
The industry response has been to separate the two targets and to pursue them in a fixed order. Content first, because it is measurable and immediately available: a recycled face with a recycled-content film is achievable on existing lines with existing parameters. Mono-material construction second, because it changes the welding window, the stiffness and the peel behaviour and has to be developed as a new construction rather than as a material swap. Brands that attempt both at once usually end up with a fabric they cannot weld consistently, and the resulting reject rate costs more than the recycled premium.
There is a durability question underneath the sustainability one, and it should be asked before the content target is set. Recycled polyester staple and filament have a shorter polymer chain than virgin material on average, and the tear strength and the abrasion figures of a recycled face at a given denier are usually a little lower. In most constructions the difference is irrelevant; in a lightweight pack where the denier has already been reduced for weight, it is the difference between a product that survives a season and one that does not. The correct response is to spend the recycled content on the face and leave the denier alone.
Direct-to-Consumer Channels Rewriting Pack Specification
The channel a bag is sold through now determines its geometry more than its use does, and this is the least discussed trend in the category. A bag sold through a marketplace is charged on dimensional weight, which means a 30-litre pack that arrives in a box measuring 60 by 40 by 40 centimetres costs more to move than its contents are worth, while the same pack shipped rolled and compressed in a poly mailer costs a third as much. A bag sold through a retail shelf has no such constraint and instead needs to stand upright and hold its shape under a price ticket.
Three specification consequences follow directly and can be designed in from the start. The first is that a direct-to-consumer product should be specified with a compressed shipping state, which means a roll-top closure, a removable frame sheet and a compressible padding build-up rather than a moulded back panel. The second is that the packaging becomes part of the product: a printed mailer, a header card and a single folded insert replace a printed box and save both volume and assembly labour. The third is that the return rate becomes a design input, and a bag that photographs larger than it is will be returned at a rate that erases the freight saving.
| Channel Requirement | Consequence for the Bag | Consequence for the Pack |
|---|---|---|
| Dimensional weight billing | Roll-top closure, removable frame, compressible padding | Poly mailer instead of a printed box |
| Retail shelf presentation | Moulded or stiffened back panel, upright stand | Printed box with a hangtag and a barcode face |
| Corporate gifting | Clean decoration area, one-colour print, retail-neutral finish | Individual sleeve or gift box, protective corner wrap |
| Subscription and kitting | Flat-packed accessories, nested components | Kitted master carton with a scan label per unit |
| Marketplace prep | Scannable label face, no loose straps in transit | Polybag with a suffocation warning and a single label |
The table is worth sharing with whoever writes the technical pack, because the packaging column is where the money is. A change from a printed box to a printed mailer typically removes more landed cost per unit than a full point of fabric negotiation, and it does so without touching the product. It also removes a carton from the freight calculation, which is why our packing figures for direct-to-consumer programmes differ from the ones used for retail, and why the structures used across the production range are specified with a compressed shipping state built in.
Automation on the Sewing Floor Since 2014
The production entity behind this programme was established in 2014, and the change on the floor between then and now is unevenly distributed. What has automated well is everything two-dimensional: automatic cutting with nesting software, programmed welding with recorded parameters, automated tape laying on straight seams, and print registration driven by a camera. What has resisted automation is everything that requires a human to judge a limp material, which includes feeding a curved panel into a folder, turning a corner on a binding, and assembling a bag inside out and righting it.
That unevenness explains a fact that surprises buyers: the operation count on a bag has fallen far less than the machine count would suggest. A 149-machine site does not run a bag through 149 operations; it runs several operations on several machines in parallel across seven lines and several products at once. The genuine gains have come from the recorded parameter set rather than from the robot: a welding cell that stores the temperature, dwell, pressure and cooling time for each model removes the variance between operators, and that variance removal is worth more to a buyer than the cycle time saved.
For a 2027 sourcing plan the conclusion is straightforward. Ask what is recorded, not what is automated. A line that stores its parameters, its peel results and its defect classification can reproduce a bag a year later; a line with impressive machinery and paper traveller cards cannot. The second question to ask is how the automatic cutter handles a print registration requirement, because that is the one place where automation and quality genuinely collide, and a printed panel that is cut two millimetres out of register ruins a waistbag regardless of how fast it was cut.
Labour Cost and Skill Pressure in Bag-Making Districts
Labour cost in the bag districts has risen steadily and, more importantly, the composition of the workforce has changed. The experienced operators who learned the trade in the 2000s are moving into supervision, and the people taking their places are trained on the job in months rather than years. That matters more in this category than in garment making, because welding and taping are parameter crafts: an operator who has not felt an under-weld cannot tell you one is there until the peel test says so.
The industry is responding in three ways, and a buyer can tell which response a site has adopted by asking one question about the welding cells. The first response is to deskill the operation by recording the parameters and fixing them, so the operator sets a job number rather than a temperature. The second is to concentrate skill, keeping a small number of senior operators on the difficult operations and rotating juniors through the simple ones. The third, which is the one to avoid, is to pay piece rates and accept the resulting variance. Ask whether the cell operator can change the welding temperature; if the answer is yes, the product quality depends on who was on shift.
Wage pressure also changes the economics of a low-operation design, and that is the point where this trend becomes actionable for a buyer. A bag specified with two fewer operations costs less to make in every district, and the saving grows as wages rise, because it removes labour rather than negotiating it. It is the single most durable cost reduction available and it does not require a change of supplier. It does require the design to be settled before the pattern is cut, which is why the trend belongs in the specification stage and not in the quotation stage.
Six Forces Ranked by Impact on a 2027 Sourcing Plan
Six forces are usually presented as six equal trends. They are not equal, and ranking them is the useful part of an industry analysis because it tells a buyer where to spend attention. The ranking below scores each force against two questions only: does it change what you should specify, and does it change which 500-piece order you should place first. Forces that change neither are background noise, however much they are discussed in the trade press.
| Force | Changes Your Specification | Changes Your First Order | Score /10 | What To Do |
|---|---|---|---|---|
| Direct-to-consumer channel shift | 5 | 5 | 10 | Design for compressed shipping; switch to a mailer |
| Recycled and mono-material fabric | 5 | 4 | 9 | Set the content target now; develop the mono build later |
| Labour cost and skill pressure | 3 | 4 | 7 | Remove two operations from the design before quoting |
| Capacity spreading across countries | 2 | 4 | 6 | Second-source the simple welded items only |
| Floor automation and parameter recording | 2 | 3 | 5 | Ask what is recorded rather than what is automated |
| Freight, tariff and input volatility | 1 | 2 | 3 | Hold the construction; shorten the reorder cycle |
The middle two rows are where most sourcing teams waste their time. Moving a second source to a new country sounds strategic and usually delivers a saving smaller than the cost of the second sampling round, the second tooling set and the second compliance file. Recording welding parameters sounds mundane and is the thing that makes the third order match the first. If the ranking does one thing, it should be to move your attention down the table rather than up it.
Freight, Tariff and Input Volatility in the Bag Trade
Freight and tariff movement is the force buyers feel most and can influence least. A container rate that triples and halves within a year changes the landed cost of a bulky low-value product dramatically, and a bag is exactly that: a large volume of air wrapped in a small weight of polymer. The two responses available are structural rather than commercial. The first is to design for a compressed shipping state so that the product itself occupies less space; the second is to shorten the reorder cycle so that less inventory sits in transit at any one time.
Input volatility works differently and is more tractable. Polymer and coating prices move with the petrochemical cycle, and the effect on a bag is felt through the fabric and film line of the quotation, which is the largest line. The buyer-side response is to fix the specification tightly enough that a fabric substitution is visible. A technical pack that says 420 denier polyester with a 0.35 mm TPU film to a stated hydrostatic head can be re-quoted against a market price; one that says heavy-duty waterproof fabric can be quietly downgraded and the saving kept.
The third kind of volatility is exchange movement, and the mechanism in this trade is simple: quotations are issued in United States dollars against FOB Xiamen terms with T/T, 30 percent deposit and 70 percent before shipment. That structure puts the freight, duty and currency-conversion exposure on the buyer after the goods are loaded, which is worth remembering when a supplier quote looks cheaper than a domestic one. The comparison has to be made on landed cost, including the container, and the packing specification is the lever that moves it.
What Industry Consolidation Does to Your Second-Source Options
Consolidation in this trade takes the form of the capable sites getting larger and the marginal ones closing, and the effect on a buyer is a narrowing of the second-source list for the difficult constructions. Fifteen years ago a buyer could find four or five sites able to weld a TPU dry bag acceptably. Today the number is larger in total but concentrated, and the consequence is that a second source for a welded product usually means a second source with less welding experience than the first.
The second consequence is that the second-source conversation has to be about a specific product rather than about a supplier. A site that is excellent at stitch-and-tape structured bags may be a poor second source for a welded roll-top, and a site that is excellent at welded products may be unable to hold a print registration on a structured panel. The practical recommendation is to second-source the simplest item in the range rather than the most profitable one, because the simple item is the one where a change of site is least likely to be noticed by the customer.
Consolidation also changes the negotiating position, and in a direction most buyers do not expect. A larger site is more interested in a 500-piece first order than a smaller one, because it treats it as an option on the third order rather than as a marginal fill-in. That is the case at the validated production partner facility behind this programme: seven lines and 200,000 pieces a month mean a 500-piece run fits as a scheduled job rather than as a favour, and the same capacity is what makes the second and fifth orders possible without a change of site.
Multi-Country Sourcing and the Quanzhou Comparison
Multi-country sourcing is the recommendation that every consultancy gives and few buyers execute well, because the comparison is usually made on the wrong axis. The axis that matters is the depth of the material and component supply around the assembly site. A bag district that has laminators, film makers, tape converters, zip factories, plating shops and moulders within a short drive can change a specification in days; a district that has to import those inputs can only change it in weeks and only if the import arrives.
| Capability | Quanzhou, Fujian | Inland Lower-Wage District | Newer Assembly Country |
|---|---|---|---|
| Laminated technical fabric supply | Local, days | Transferred, 1 to 2 weeks | Imported, 3 to 6 weeks |
| Waterproof zip and moulded hardware | Local, days | Transferred, 1 to 2 weeks | Imported, 4 to 8 weeks |
| RF welding experience on TPU | Widespread | Limited | Nascent |
| Lot-level test documentation | Routine, in-house | Usually external | Usually external |
| Realistic first-sample lead time | 6 to 10 working days | 10 to 18 working days | 15 to 25 working days |
| Suitability for welded dry bags | High | Low | Low |
| Suitability for sewn structured bags | High | High | Moderate |
The last two rows are the ones that should drive the decision, and they point in opposite directions for opposite products. A welded product should stay where the welding skill and the film supply are, because a welded seam is a parameter problem and parameters are learned locally. A sewn structured product can move, because sewing is a transferable skill and the inputs are more standardised. That is the actual shape of a sensible multi-country plan, and it is more specific than the recommendation usually given.
What Demand Spikes Do to Your 35-50 Day Slot
Bulk production at this site takes 35 to 50 days from approved sample to goods ready for loading, and that range exists because it is a scheduling range rather than a manufacturing one. The physical work on a 500-piece order occupies a small part of it; the rest is the queue for the line, the queue for the printed panels, the queue for the bought-in hardware and the queue for the fabric roll. A demand spike elsewhere in the category lengthens all four queues at once, and the effect on a small order is proportionally larger than on a large one.
The buyer-side lever is to remove items from the queue before the order is placed rather than to ask for a shorter slot afterwards. Confirming the fabric at the same time as the sample approval removes the longest queue, because a laminated roll is a purchased item with its own lead time. Standardising the hardware to a part held in stock removes the second. Approving the print at the sampling stage rather than at the pre-production stage removes the third. All three are free, and all three have to be done before the deposit is paid rather than after.
The fourth queue is the production slot itself, and there is one structural way to shorten it: keep the construction unchanged across the order. A model that has been run before has a recorded parameter set, a filed pattern and a known operation count, so it can be scheduled into a slot without a development window ahead of it. That is the real reason to limit the number of new constructions in a first year, and it is the strongest argument against redesigning a product on the strength of a trend before the second order has been placed.
Sector Demand Shifts Across Paddle, Jobsite and Care
Three end-use sectors have grown faster than the category average and each one pulls the specification in a different direction. Paddle sports, meaning kayaking, rafting and stand-up paddling, demands genuine immersion performance and therefore welded seams, roll-top closures and a stated immersion rating to IEC 60529. It is also the sector where the lowest volume colourways are sold, which makes the 500-piece minimum a genuine constraint and pushes brands towards a shared-shell range.
Jobsite and field-service demand pulls the opposite way, towards abrasion, puncture and organisation rather than immersion. The specification consequence is a higher denier, a coated or laminated base that can be wiped down, a reinforced bottom panel and an internal frame that will not collapse when the bag is set down in a puddle. It is the sector where stitch-and-tape beats welding, because the geometry is three-dimensional and the load paths are concentrated at the strap roots. It is also the sector where a mono-material build most easily fails on abrasion, so it should be the last one to adopt it.
Care and healthcare demand pulls towards cleanability and documentation, and it is the most regulated of the three. The bag has to tolerate a wipe-down with a disinfectant without the print lifting or the film hazing, which is a chemical resistance question rather than a waterproofing one, and it brings a CPSC-facing file where the product is sold for children, plus a registration consideration where a fluid-resistance claim is made. Our quality and documentation page lists the file set that the care sector usually asks for, and the same page covers the AQL 2.5 inspection that all three sectors should receive.
Reading an Industry Trend Before You Commit 500 Pieces
Most trend reports are written for investors and are of limited use to somebody about to place a first order, which is why the structure of a first custom programme should be settled before any trend is applied to it. A useful trend analysis for a buyer has to clear three tests before it changes a technical pack, and the tests are worth applying to anything published, including this page. The first is a unit test: does the trend change a number on your specification, such as a denier, a weld width, a closure type or a carton size? If it does not, it is commentary. The second is a timing test: does it affect this order or the one after next? The third is a reversibility test: if the trend is wrong, can you undo the change without a new tooling charge?
- Write the change as a number. Recycled content becomes a stated percentage; lightweighting becomes a stated denier and a stated coating weight.
- Attach a test method to each number, typically ISO 811 for hydrostatic head and AATCC 22 for the spray grade of the face.
- Decide whether the change is reversible. A colourway is reversible, a tooled closure is not, and a new film is not.
- Put the reversible changes in this order and the irreversible ones in the one after, because the second order is where you will know whether the trend was real.
- Keep one construction unchanged as the control, so that the effect of the trend change can be measured against something.
- Re-read the trend in twelve months against your own return and complaint data rather than against the report that predicted it.
The fifth item is the one that gets skipped and the one that saves money. A brand that adopts three trend-driven changes in a single season, and then sees complaints rise, cannot tell which change caused them. A brand that changes one thing and holds the rest has a usable experiment and, twelve months later, a defensible reason for the second season's technical pack. The same logic is why we recommend a single-colour first run, and it costs nothing to adopt.
Compliance Documents the Industry Now Expects by Default
Five years ago a compliance file was requested by a minority of buyers, mainly those selling into European retail. It is now the default expectation across most channels, and the file has a standard shape. ISO 9001:2015 covers the documented quality management system and carries a scope that must name bags. BSCI is the social compliance audit on the site and carries a name, a date and a headcount. REACH covers restricted substances in the articles, RoHS covers the electrical and electronic content, and OEKO-TEX is increasingly requested on the textile components as a retail policy rather than a legal requirement.
On top of the chemical and social file sits the performance evidence, and this is where the industry has tightened most. A hydrostatic head claim now has to be supported by a result to ISO 811 or AATCC 127, a spray grade by AATCC 22, a rain result by AATCC 35, and an immersion claim by IEC 60529 with a stated depth and duration. A quality claim without a method named beside it is now treated by most serious buyers as no claim at all. The inspection side is standardised too: AQL 2.5 under ISO 2859-1 is the accepted sampling rule, and the classification of critical, major and minor defects should be agreed in writing before production starts.
The trend to watch is that this file is moving upstream, from the finished article to the roll. Retailers increasingly want the fabric lot certificate rather than the product test report, because the lot certificate is what makes the fourth order match the first. That is a change a supplier can only meet if they buy in roll lots with a number on each one, which is a purchasing discipline rather than a testing capability. If you want the file set for a specific construction, write to service@junyuanbags.com or message WhatsApp +86 177 5002 0688.
Frequently Asked Questions
Q1: Is bag manufacturing leaving China?
A: Partly, and the split matters. Labour-intensive cutting, sewing and assembly have spread to lower-wage districts and newer assembly countries, while the material base of laminated technical fabric, waterproof zips and moulded hardware has stayed clustered. A country can advertise a finished bag industry while importing the two inputs that determine whether the bag is waterproof.
Q2: Which products should a brand second-source outside China?
A: Sewn structured products, because sewing is a transferable skill and the inputs are standardised. Welded products should stay near the welding skill and the film supply, since a welded seam is a parameter problem and parameters are learned locally rather than moved in a container.
Q3: How much recycled content should I specify?
A: Set the content target first and treat it as a percentage of the face fabric plus the film, because a recycled face laminated to a virgin film is still a laminate that mechanical recyclers will reject. Develop the mono-material construction afterwards, since it changes the welding window and needs its own development.
Q4: Does recycled fabric perform as well as virgin?
A: Slightly less well at the same denier, because recycled polyester has a shorter average polymer chain and therefore lower tear and abrasion figures. In most constructions the difference is irrelevant; in a lightweight pack where the denier has already been reduced, it is the difference between surviving a season and not.
Q5: Why does the direct-to-consumer channel change bag design?
A: Because marketplaces bill on dimensional weight, so a 30-litre pack that ships in a rigid box costs more to move than its contents are worth. A direct-to-consumer product should be designed to ship compressed, with a roll-top closure, a removable frame and compressible padding instead of a moulded panel.
Q6: How long does bulk production take and can it be shortened?
A: Thirty-five to fifty days from approved sample to goods ready for loading. Most of that is queueing rather than manufacturing, so the effective lever is to remove items from the queue before the order is placed by confirming the fabric, the hardware and the print at the sampling stage.
Q7: What has automation actually changed on the bag floor?
A: Two-dimensional operations have automated well, including nesting and cutting, programmed welding, automated tape laying and camera-driven print registration. Operations requiring a human to judge a limp material have resisted automation, which is why the operation count has fallen far less than the machine count suggests.
Q8: What should I ask about labour and skill at a bag site?
A: Ask whether the welding cell operator can change the welding temperature. If the answer is yes, quality depends on who was on shift. The better sites deskill the operation by recording the parameters and fixing them, so the operator sets a job number rather than a temperature.
Q9: How does freight volatility affect a bag programme?
A: Strongly, because a bag is a large volume of air wrapped in a small weight of polymer and so is billed on volume. The two structural responses are to design for a compressed shipping state and to shorten the reorder cycle so less inventory sits in transit.
Q10: Which compliance documents are now default in the bag industry?
A: ISO 9001:2015 with a scope naming bags, a BSCI social audit, REACH and RoHS declarations, and OEKO-TEX on textile components where a retailer requires it. Performance evidence is now expected too, with a named method such as ISO 811, AATCC 22 or IEC 60529 beside every claim.
Q11: What is the AQL standard used for bag inspection?
A: AQL 2.5 under ISO 2859-1 is the accepted sampling rule for finished cartons. It is a statistical rule rather than a promise about any individual bag, so the critical, major and minor classification should be agreed in writing before production begins.
Q12: Which end-use sectors are growing fastest?
A: Paddle sports, jobsite and field service, and care. Paddle demands welded seams and an immersion rating, jobsite demands abrasion and organisation and suits stitch-and-tape, and care demands cleanability plus the heaviest documentation load of the three.
Q13: How should I apply a trend report to my own range?
A: Apply three tests. The trend must change a number on your specification, it must affect a specific order rather than an indefinite future, and it must be reversible if it turns out to be wrong. Anything that fails the first test is commentary rather than a sourcing input.
Q14: Why keep one construction unchanged when adopting a trend?
A: So you have a control. A brand that makes three trend-driven changes at once and then sees complaints rise cannot tell which change caused them, while a brand that changes one thing and holds the rest has a usable experiment to read twelve months later.
People Also Ask
- Where are waterproof bags manufactured now?
- Is Vietnam a good alternative for bag sourcing?
- How is the bag industry changing?
- What is driving recycled fabric adoption in bags?
- How does e-commerce change bag design?
- What compliance files do bag buyers need?