
Waterproof Bag Import Guide: HS Codes and Clearance
Most waterproof bags are classified in HS heading 4202, and the subheading depends on the outer surface material and on the construction rather than on what the product is called. Get the subheading right and the duty rate, the preference eligibility and the documentation set all follow from it; get it wrong and a shipment can be held, reclassified and penalised. QUANZHOU JUNYUAN BAGS supplies the material and construction statements that make a classification defensible, shipping FOB Xiamen since 2014 with a founder in the trade since 2004.
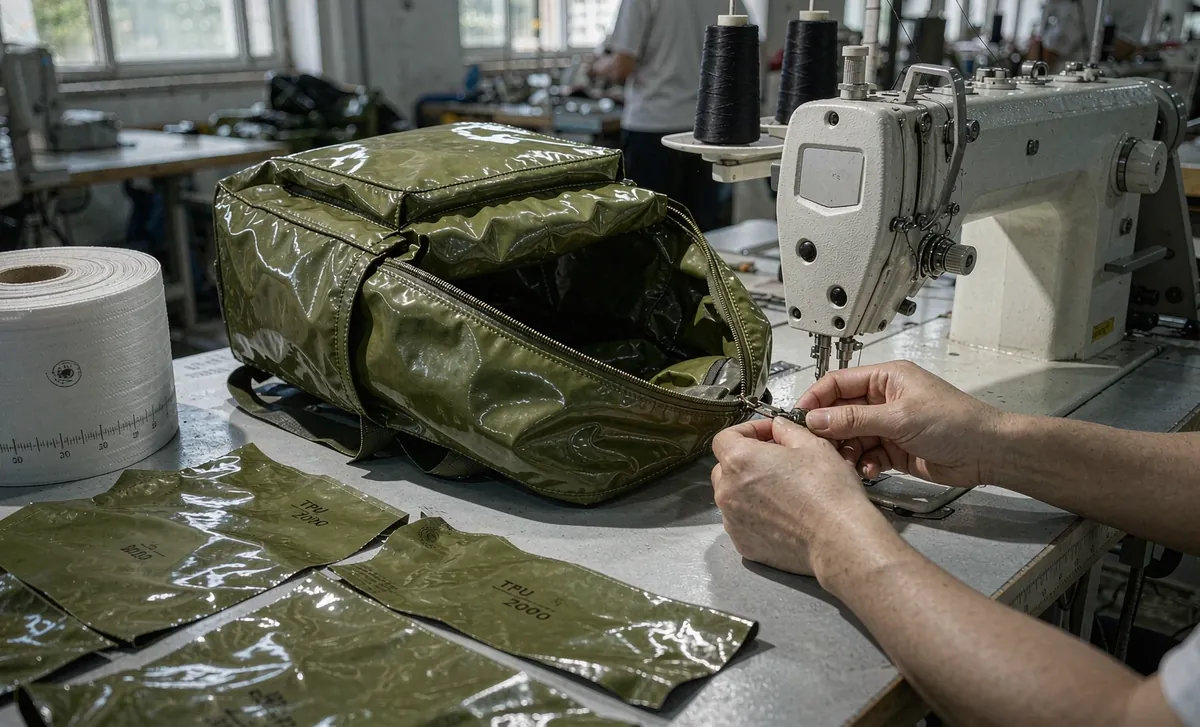
Table of Contents
- HS Heading 4202: How a Waterproof Bag Is Classified
- Four Subheading Paths and the Test for Each
- The Document Set for a First Import Shipment
- Invoice, Packing List and Bill of Lading Consistency
- Country of Origin and the Rules That Attach It
- Preference Programmes: FORM E and RCEP Certificates
- How Duty and VAT Are Calculated on Entry
- US Entry: ISF Filing, Bond and Entry Summary
- EU Entry: EORI, Declaration and Import VAT
- Nine Conditions That Get a Shipment Held
- Binding Rulings and Classification Disputes
- Labelling and Marking Rules at the Destination
- A Twelve-Step Walkthrough for a First Import
- Records to Retain and for How Long
- Frequently Asked Questions
- People Also Ask
HS Heading 4202: How a Waterproof Bag Is Classified
Classification is the foundation of an import, and it is decided by the physical characteristics of the goods rather than by the commercial name on the invoice. Heading 4202 covers trunks, suitcases, handbags and similar containers, and the subheading is selected by working down a series of tests: what the outer surface is made of, whether the bag is of a kind normally carried in the pocket or handbag, and what the construction is.
The first and most consequential test for a waterproof bag is the outer surface. A bag whose outer surface is of sheeting of plastics or of textile material impregnated or laminated with plastics falls in a different subheading from one whose outer surface is of textile material without that treatment. A welded TPU dry bag and a stitched polyester day pack can therefore sit in different subheadings even when they look similar in a catalogue.
This is why the classification decision has to be made from the material specification, not from the product name. The importer needs three statements from the manufacturer: what the outer surface consists of, whether it is impregnated, coated, covered or laminated with plastics, and whether the plastics layer is visible to the naked eye. Those three answers, given in writing, are what a customs officer will test the declaration against.
The second consequence is that classification is not a matter of opinion to be settled later. It determines the duty rate, whether a preference programme applies, whether any quota or additional measure attaches, and what the importer must declare. A brand that treats it as paperwork to be completed after the goods ship is taking a risk that is entirely avoidable, and the export and import guide carries the wider commercial context.
Four Subheading Paths and the Test for Each
In practice a waterproof bag programme will land in one of four paths within heading 4202, and the path is determined by the outer surface and by the intended use. The table below sets out the test for each and the evidence that supports it. The rates are not given here because they are set by the destination tariff and change; the subheading is what you need to look up.
| Subheading path | Outer surface test | Typical product | Evidence to hold on file | Where it goes wrong |
|---|---|---|---|---|
| Plastic sheeting outer surface | Outer surface is sheeting of plastics | Welded PVC tool bag, dry bag | Material spec with film gauge and polymer | A laminate mistaken for a coating |
| Textile with plastics laminate | Textile impregnated, coated or laminated with plastics | TPU-laminated backpack | Lamination construction statement | Whether the plastics layer is visible |
| Textile without plastics treatment | Outer surface is textile material | Canvas or untreated shell bag | Face cloth specification only | A finish mistaken for a coating |
| Other containers of a kind carried daily | Of a kind normally carried in pocket or handbag | Small waterproof pouch | Size and intended carry statement | Pouches argued into a larger class |
The row that generates the most disputes is the second one, because a laminate and a coating look identical on a finished bag and are described identically in casual conversation. The distinction matters: a laminate is a film bonded to the cloth, a coating is applied as a liquid or paste, and the tariff language treats impregnation, coating, covering and lamination differently. Ask the manufacturer to state which construction it is in writing, and keep that statement with the entry.
The fourth row is where small waterproof items cause trouble. A phone pouch or a wallet is of a kind normally carried in the pocket or handbag and is classified accordingly, while a larger dry bag is not. Importers frequently declare the whole shipment under the subheading for the largest item to keep the paperwork simple, which is a classification error that a physical inspection will find immediately.
Where a shipment genuinely contains items falling in more than one subheading, declare them separately. A mixed shipment declared at the highest rate is not a safe choice; it is a misdeclaration, and it also forfeits any preference that would have applied to the lower-rated lines. Separate lines on the invoice are a small amount of work and remove the question.
The Document Set for a First Import Shipment
A first import fails more often on documentation than on goods. The set below is what a broker will ask for, and the useful discipline is to assemble it before the vessel sails rather than after it arrives, because several of the items have a lead time and cannot be produced retrospectively.
- Commercial invoice showing seller, buyer, description, quantity, unit and total value, and the declared classification.
- Packing list showing carton count, contents per carton, net and gross weight, and carton dimensions.
- Bill of lading or airway bill, with the consignee and notify party matching the broker's instructions.
- Certificate of origin, and where a preference is claimed, the specific preference certificate for the programme.
- Material and construction statement supporting the classification, held on file with the entry.
- Restricted-substance documentation where required, such as REACH and RoHS declarations for the European market.
- Any product-specific certificate the destination requires, such as a children's product certificate under CPSC rules.
Two of these are commonly missing. The material and construction statement is not a standard trade document, which is why nobody asks for it until a classification is questioned, and by then the goods are already on the quay. Request it from the manufacturer at the same time as the invoice, and file it with the entry rather than in a folder somewhere else.
The second missing item is the certificate of origin issued by the competent authority rather than a statement printed on supplier letterhead. A preference claim requires the specific certificate for the programme, issued by the authorised body, with the correct origin criterion stated. A self-printed origin statement will be rejected, and the duty saving is lost along with the time spent arguing about it.
Invoice, Packing List and Bill of Lading Consistency
The three core documents describe the same shipment in three ways, and customs systems compare them. Any disagreement between them is a query, and a query is a delay with a daily cost. The check is mechanical and takes ten minutes, and it should be done before the documents are sent rather than after the container lands.
| Field | Invoice | Packing list | Bill of lading | Must agree on |
|---|---|---|---|---|
| Consignee name and address | Yes | Not always | Yes | Exact legal name and address |
| Number of cartons | Total only | Per carton breakdown | Yes | Same total carton count |
| Total piece count | Yes | Yes | Not stated | Same quantity of goods |
| Gross weight | Yes | Yes | Yes | Same figure to the same rounding |
| Goods description | Full description | Short description | Short description | Same product and same material |
| Country of origin | Yes | Sometimes | Yes | Same origin statement |
Weight is the field that disagrees most often, because the invoice is prepared from the order, the packing list from the packed cartons, and the bill of lading from the carrier's weighing. One or two kilograms across a container is normal variance; a discrepancy of ten percent invites a physical examination. Weigh the finished cartons, use that figure on all three documents, and state the tolerance in the packing list if the carrier's scale differs.
The goods description is the second problem area. A description that says bag on the invoice and waterproof dry bag, TPU laminated on the packing list looks like two different products to an automated risk system. Write one description, use it on all three documents, and make sure that description is consistent with the classification being declared.
Country of Origin and the Rules That Attach It
Origin is not the same as the country the goods shipped from. Non-preferential origin is determined by where the last substantial transformation took place, and preferential origin is determined by the specific rules of the programme being claimed. A bag assembled in one country from film and cloth made in another can have a different origin under each test, and the two answers have different consequences.
For a waterproof bag, the transformation question usually turns on whether cutting and welding the panels constitutes substantial transformation of imported material, or whether the material itself determines origin. The answer depends on the destination's rules, and it is answered by the manufacturing record rather than by an assertion. This is why the manufacturer's process description matters to the importer, and why it should be requested before the first shipment.
Marking follows from origin. Most destinations require the country of origin to be marked on the product or on the retail packaging in a way that is legible, permanent and visible to the ultimate purchaser. A mark printed on an insert that is discarded at unpacking is not adequate, and a mark sewn into an internal seam that cannot be seen without unpacking the bag is frequently challenged.
Transshipment is the third issue. A shipment routed through a third country's port does not change origin, but it does add a documentation requirement, because the customs authority will want to see that the goods were not altered in transit. Keep the through bill of lading and any transshipment record with the entry, and declare the routing honestly.
Preference Programmes: FORM E and RCEP Certificates
A preference programme reduces or eliminates duty where the goods originate in a participating country and meet that programme's rules. Eligibility is not automatic for goods shipped from a participating country; it has to be established against the product-specific rule and then documented on the correct certificate. Claiming a preference without the certificate is worse than not claiming it, because it invites a verification.
| Programme | Certificate used | What establishes eligibility | Common failure | Practical note |
|---|---|---|---|---|
| ASEAN trade arrangement | FORM E | Origin criterion met and stated | Criterion left blank or wrongly stated | Issued by the competent authority before shipment |
| RCEP | RCEP certificate of origin | Origin criterion under the agreement | Wrong origin criterion for the material | Check which members have ratified for your lane |
| Generalised preference schemes | Form A or equivalent | Origin plus the scheme's conditions | Scheme withdrawn for the country | Confirm current eligibility before quoting |
| Bilateral arrangements | Programme-specific form | Product-specific rule of origin | Rule misread as change of heading only | Read the rule text, not the summary |
The single most common failure is the origin criterion field. A certificate that states origin without stating the criterion by which origin was established is incomplete, and customs will treat the claim as unsupported. The criterion has to be derived from the product-specific rule for the subheading, which is why the classification step has to be right before the preference step is attempted.
Timing is the second issue. Preference certificates are issued before or at shipment, not retrospectively, and a certificate produced after the goods have arrived is generally not accepted for that entry. Build the certificate into the pre-shipment document checklist alongside the invoice and the packing list, and give the manufacturer the consignee details early enough for it to be issued correctly.
How Duty and VAT Are Calculated on Entry
Duty is a percentage of the customs value, and the percentage is the rate published in the destination tariff for the subheading that was declared. Because rates change and differ between destinations, the only reliable method for an importer is to look up the current rate for the confirmed subheading in the destination's own tariff rather than to rely on a figure quoted in a conversation.
The calculation itself is a sequence. Establish the customs value, which is normally the transaction value adjusted for any elements the destination requires to be added, such as freight and insurance to the frontier where the destination values on that basis. Apply the published duty rate to that value. Then apply import VAT or sales tax to the value plus the duty, and add any destination handling charges.
Two additions are routinely omitted from a first landed-cost model. The first is that VAT or sales tax is charged on the duty-inclusive value in most destinations, so duty raises the tax base as well as adding to cost. The second is that some destinations apply an additional fee based on shipment value or on the mode of entry, which is small per entry and real across a season.
The practical consequence for a brand is to build the landed cost with the duty rate as a variable rather than as a fixed number, and to re-check it at specification freeze and again before the second order. A classification change or a tariff revision between two orders is enough to move the margin on a promotional product, which is why the classification should be confirmed in writing at the start.
US Entry: ISF Filing, Bond and Entry Summary
Entry into the United States has three formal steps that catch first-time importers. The first is the importer security filing, which must be lodged before the goods are loaded onto a vessel for the United States. The second is a customs bond, which is required for formal entry and can be single-entry or continuous. The third is the entry summary, which declares the classification, value and duty.
The importer security filing is the one that causes avoidable penalties, because its deadline is tied to loading rather than to arrival. A shipment booked a week before sailing needs the filing data within that week, which means the manufacturer has to supply the consignee details, the classification and the container stuffing location earlier than they would for any other destination. Tell the supplier the destination is the United States at the order stage, not at the booking stage.
Classification-specific documentation also matters here. Where a bag is marketed to children, CPSC rules apply and a children's product certificate is required, supported by testing on the finished article. Where a restricted-substance position is requested by a retailer, that documentation sits alongside the entry rather than replacing it. The US import compliance page sets out the sequence in detail.
One more practical point: the party named as importer of record carries the liability for the declaration. A brand that lets a logistics provider act as importer of record without understanding what is being declared has transferred the liability but not the commercial risk, because a penalty and a delay land on the goods either way. Know which subheading is being declared on your behalf.
EU Entry: EORI, Declaration and Import VAT
Entry into the European Union requires an economic operators registration and identification number for the importer, a customs declaration lodged through the member state's system, and payment or deferment of import VAT. The declaration carries the classification, the customs value and the origin, and it is the document against which a post-clearance audit is conducted.
The product-side requirements run alongside the customs-side ones. A restricted-substance position against REACH and RoHS is expected by most European retail buyers and is frequently a condition of listing rather than of import. Where the product has skin contact, OEKO-TEX criteria are often requested. These are commercial documents in the strict sense, but they are assembled from the same material data as the customs file.
Import VAT is the cash-flow item. In most member states it is payable at import and recoverable by a VAT-registered importer, which means the cash is out for a period and then reclaimed. A first-time importer modelling landed cost should treat import VAT as a working-capital item rather than as a cost, and should confirm the deferment or recovery mechanism before the first container arrives.
Nine Conditions That Get a Shipment Held
A hold is expensive because it is charged by the day and because it happens at the least flexible point in the chain. The nine conditions below account for most holds on bag shipments, and every one of them is preventable at the documentation stage.
- The declared classification does not match the goods description on the invoice.
- Weight or carton count differs between the invoice, the packing list and the bill of lading.
- Country-of-origin marking is missing, illegible or placed where it cannot be seen.
- A preference is claimed without the correct certificate issued by the competent authority.
- The importer of record details do not match the registration on file.
- A required product certificate is absent, such as a children's product certificate under CPSC rules.
- Restricted-substance documentation requested by the retailer has not been supplied.
- The consignee on the bill of lading differs from the consignee the broker was instructed to clear for.
- Value declared is inconsistent with the payment record, which invites a valuation query.
The cheapest control is a pre-shipment document review. Send the draft invoice, packing list and certificate set to the broker while the goods are still in production, and let the broker check them against the entry they intend to lodge. That review costs an hour and removes most of the nine conditions above before they become a demurrage bill.
Binding Rulings and Classification Disputes
Where a classification is genuinely uncertain, the answer is a binding ruling rather than a guess. Most customs administrations will issue a written ruling on the classification of a described product, and that ruling binds the administration for future entries of the same goods. It takes time to obtain, which is why it belongs in the product development phase rather than in the shipping phase.
A ruling application is a description exercise. It needs the material composition, the construction, the dimensions, the intended use and, usually, a physical sample or photographs. A waterproof bag application should state whether the outer surface is a laminate or a coating, because that is the fact on which the subheading turns, and it should state it in the same words the manufacturer uses on the material specification.
If a dispute arises instead, respond with evidence rather than argument. The persuasive documents are the material specification, the construction statement, photographs of the product and, where available, a laboratory result confirming the composition. An assertion that the goods are a bag of a particular kind is not evidence; a statement that the outer surface is a 0.15 mm TPU film laminated to 840D nylon is.
Labelling and Marking Rules at the Destination
Labelling is enforced after import rather than at it, which is why it is so often discovered late. A shipment can clear customs perfectly and then be refused by a retailer, or recalled from shelves, because the marking does not meet the destination's rules. The requirements are per destination and they attach to the retail pack rather than to the shipping carton.
Three marking elements apply almost everywhere. Country of origin must be legible, permanent and visible to the ultimate purchaser. Fibre content must be stated where the product has a textile content, in the prescribed form. Care instructions must be present where a care claim is made, and for a waterproof bag the care instruction matters commercially because it tells the owner how to preserve the finish.
The labelling and packaging page carries the field list we work from, and the compliance documentation for the shipment is issued with the inspection records from the quality programme.
A Twelve-Step Walkthrough for a First Import
For a brand importing waterproof bags for the first time, the sequence below is the order that avoids rework. The steps that are most often done out of order are the classification, which should precede the quotation, and the broker review, which should precede shipment rather than follow arrival.
- Fix the material specification, including whether the outer surface is a laminate or a coating.
- Confirm the subheading for that specification in the destination tariff, and record the published rate.
- Where the classification is uncertain, apply for a binding ruling before production.
- Appoint a broker and give them the specification, not just the product name.
- Confirm origin and whether any preference programme applies, and which certificate it needs.
- Order the goods with the destination stated at the order stage, so document deadlines are known.
- Request the material and construction statement at the same time as the commercial invoice.
- Arrange the certificate of origin from the competent authority before shipment.
- Assemble the restricted-substance and product certificates required by the destination and the retailer.
- Send the draft document set to the broker for review while goods are still in production.
- Lodge any pre-shipment filing the destination requires, such as an importer security filing for the United States.
- On arrival, reconcile the entry against the documents and file the whole set together.
Following the sequence costs nothing extra and removes the two failure modes that dominate first imports: a classification discovered after the goods have shipped, and a document set assembled after the vessel has arrived. Both are entirely within the importer's control, and both are cheaper to prevent than to fix.
Records to Retain and for How Long
Customs retention periods are set by the destination and are typically several years from the date of entry, and a post-clearance audit will ask for the entry record and everything that supported it. The practical rule is to keep the full set for at least five years and to keep it as one package per shipment rather than scattered across email.
| Record | Who produces it | Why it is needed | Retention note |
|---|---|---|---|
| Commercial invoice and packing list | Manufacturer | Proves value, quantity and description | Keep the final version sent to the broker, not the draft |
| Bill of lading | Carrier | Proves routing and receipt | Keep including any transshipment record |
| Certificate of origin | Competent authority | Supports the preference claim | Keep with the origin calculation |
| Material and construction statement | Manufacturer | Supports the classification | Keep with the entry, not separately |
| Restricted-substance declarations | Manufacturer or laboratory | Supports REACH and RoHS positions | Keep the version for the actual production lot |
| Inspection report | Manufacturer or inspector | Supports quality and quantity | Keep with the AQL 2.5 record under ISO 2859-1 |
The row that is almost always missing at audit is the material and construction statement, because it is not a standard trade document and nobody thinks to file it. It is the document that answers the only question an auditor will actually ask about a waterproof bag: what is the outer surface made of. Request it with every shipment and file it with every entry.
QUANZHOU JUNYUAN BAGS issues the material and construction statement, the inspection report to AQL 2.5 under ISO 2859-1 and the restricted-substance declarations with each shipment, quoted FOB Xiamen with T/T 30 percent deposit and 70 percent before shipment. Sampling runs 6 to 10 working days and bulk 35 to 50 days. Send a specification and a destination to service@junyuanbags.com or WhatsApp +86 177 5002 0688, or start from the contact page.
Frequently Asked Questions
Q1: What HS code applies to a waterproof bag?
A: Most waterproof bags fall within heading 4202, and the subheading depends on the outer surface material and the construction rather than on the product name. A welded bag with a plastics sheeting outer surface is classified differently from a TPU-laminated textile bag. Confirm the material first, then look up the current rate for that subheading in the destination tariff.
Q2: Why does the laminate versus coating distinction matter for classification?
A: Because the tariff language treats impregnation, coating, covering and lamination differently, and the subheading turns on which construction the outer surface is. A laminate is a film bonded to the cloth and a coating is applied as a liquid or paste, and they look identical on a finished bag. Get the manufacturer to state which one it is in writing.
Q3: What documents does a first import of waterproof bags need?
A: A commercial invoice, a packing list, a bill of lading, a certificate of origin from the competent authority, a material and construction statement supporting the classification, and any destination-specific product certificate such as a children's product certificate under CPSC rules. Restricted-substance declarations cover REACH and RoHS for the European market.
Q4: Why do shipments get held at customs?
A: Nine conditions account for most holds: a classification that does not match the invoice description, weight or carton count differences across the three core documents, missing origin marking, a preference claimed without the right certificate, importer details that do not match the registration, and an absent product certificate.
Q5: What is the importer security filing and when must it be lodged?
A: It is a pre-arrival filing required for vessel shipments to the United States, and its deadline is tied to loading rather than to arrival. That means the consignee details, classification and stuffing location have to reach the broker while the goods are still being loaded. Tell the supplier the destination is the United States at the order stage.
Q6: How is duty calculated on an imported bag shipment?
A: Duty is the published rate for the declared subheading applied to the customs value, which is normally the transaction value adjusted as the destination requires. Import VAT or sales tax is then charged on the value including duty in most destinations, so duty raises the tax base as well as adding cost. Treat the rate as a variable.
Q7: Do I need a certificate of origin for a preference claim?
A: Yes, and it must be the certificate for the specific programme, issued by the competent authority with the origin criterion stated. A statement printed on supplier letterhead will be rejected. The criterion has to follow from the product-specific rule for the subheading, which is why the classification must be confirmed first.
Q8: What is the origin criterion and why does it matter?
A: It is the rule by which the goods are shown to originate in a participating country, and it is derived from the product-specific rule of origin for the subheading. A certificate that states origin without stating the criterion is incomplete, and the preference claim will be treated as unsupported, with the duty saving lost.
Q9: How should country of origin be marked on the product?
A: Legibly, permanently and in a place where the ultimate purchaser will see it. A mark on an insert discarded at unpacking is not adequate, and a mark inside a seam that cannot be seen without unpacking the bag is frequently challenged. The marking obligation attaches to the retail pack rather than to the shipping carton.
Q10: What should a binding ruling application contain?
A: A description of the material composition, the construction, the dimensions and the intended use, usually with a sample or photographs. For a waterproof bag it should state whether the outer surface is a laminate or a coating and in the same words the manufacturer uses on the material specification. Apply during development, not during shipping.
Q11: What happens if customs disputes my classification?
A: Respond with evidence rather than argument. The persuasive documents are the material specification, the construction statement, photographs and any laboratory result confirming composition. An assertion that the goods are a bag of a particular kind is not evidence; a statement that the outer surface is 0.15 mm TPU laminated to 840D nylon is.
Q12: What labelling rules apply after import?
A: Country of origin, fibre content where there is a textile content, and care instructions where a care claim is made. Language requirements apply per market, so a product sold in several member states needs the required information in each language. These attach to the retail pack and are enforced after import rather than at it.
Q13: Should a mixed shipment be declared under one subheading?
A: No. Where items genuinely fall in different subheadings, declare them separately on separate invoice lines. Declaring everything at the highest rate is a misdeclaration rather than a safe choice, and it also forfeits any preference that would have applied to the lower-rated lines.
Q14: How long should import records be kept?
A: Retention periods are set by the destination and are typically several years from the date of entry. A practical rule is at least five years, kept as one package per shipment rather than scattered across email. Include the material and construction statement, which is the record most often missing at a post-clearance audit.
Q15: What is the role of the importer of record?
A: The importer of record carries the liability for the declaration, including classification, value and origin. A brand that lets a logistics provider act in that role transfers the liability but not the commercial risk, because a penalty and a delay land on the goods either way. Always know which subheading is being declared on your behalf.
Q16: What are the commercial terms on an import order?
A: 500 pieces per style per colour, sampling in 6 to 10 working days, bulk in 35 to 50 days after sample approval, inspection to AQL 2.5 under ISO 2859-1, quoted FOB Xiamen with T/T 30 percent deposit and 70 percent before shipment. The material and construction statement and inspection report are issued with each shipment.
People Also Ask
- What HS code is used for waterproof bags?
- How do I import bags from China step by step?
- Do I need a certificate of origin for bags?
- What documents are needed to clear customs for bags?
- How is import duty calculated on bags?
- Why was my shipment held by customs?